Is the North Queensland management rights market stable, flat or beginning to recover? Speak to those working across sales, accounting and valuations and the answer is, perhaps confusingly, all three.
Operationally, many established businesses are performing steadily. Holiday occupancy and tariffs have strengthened, profitability is generally holding and tourism demand remains sound.
The sales market is a different story. Enquiry has softened, buyers are taking longer to commit and every aspect of a business is being examined more closely before a contract reaches settlement.
The distinction is important. A slower sales market does not necessarily mean the businesses themselves are struggling.
Put simply, the businesses are doing their job. Buyers are just taking their time.
CBMR Director and management rights specialist Calvin Bailey described the current sales market as “pretty flat”, following a much stronger period.
“The market was strong late last year and early this year, with record numbers of enquiries. Then at the end of February, it was as if the light was abruptly switched off.”
He attributes much of that change to wider economic and geopolitical uncertainty, cost-of-living pressures and weaker confidence among prospective buyers from New Zealand and Australia’s southern states.
“People are totally adopting a ‘wait and see’ approach.”
However, he stressed that the decline in enquiries should not be interpreted as a fundamental problem with the industry.
“The softer enquiry levels currently being experienced in the management rights sector are primarily driven by broader economic uncertainty rather than any fundamental weakness in the industry itself,” he said.
Operational performance remains steady
From an accounting perspective, Miriam Eagle, Director and FCPA, is not seeing evidence of a dramatic change in the financial performance of North Queensland management rights businesses.
“Stable and steady. We are not seeing any dramatic decline or increases over our client base. Profitability is steady, so operator confidence is similar. Nobody is expecting any great decline or uplift,” she said.
Robert Cuda, Director of Caatz Management Rights Accountants described 2026 as a year of two halves.
Trading softened during the early months as higher travel costs affected airfares and drive-market demand. Conditions changed considerably with the arrival of the region’s traditional winter season.
“Since June, the high season has been exceptional. Occupancy and rates through the winter months have been well ahead of what the first half of the year suggested,” he said.
Valuation evidence also points to sound underlying trading conditions.
Accom Valuers Director-Valuer Alex McCowan said the Cairns and Port Douglas market had remained reasonably steady over the past two years, with sales occurring across both short-term holiday and long-term permanent management rights businesses.
“Trading and visitation have returned to pre-COVID level or better in most cases,” he said.
Valuations undertaken by Accom Valuers during 2025 and 2026 recorded occupancy levels ranging from 60 to 87 percent and average daily tariffs between $206 and $313 per night.
There may be no dramatic boom, but there is no dramatic decline either. Well-run businesses with reliable income and strong local demand are continuing to trade well.

Seasonality remains fundamental
The figures also need to be considered in the context of North Queensland’s pronounced seasons.
“Holiday letting in North Queensland is unavoidably seasonal, with the high season running from June to September, when tourists want to visit the tropics,” Robert Cuda said.
“What separates the astute operators is how deliberately they manage the shoulder and off-peak periods.”
Successful managers are targeting corporate travel, monitoring major events and sporting calendars, and adjusting their marketing to lift occupancy outside the winter peak.
Robert believes that seasonality is also one reason Far North Queensland management rights businesses can offer attractive returns compared with their southeast Queensland counterparts.
Buyers need to understand the region’s seasons, but they can often enter at lower multipliers and achieve a stronger return on investment.
Costs are rising
Stable revenue does not mean operators are escaping financial pressure.
Cost inflation remains one of the most significant challenges, particularly across cleaning labour, linen and insurance. Following the 2026 Annual Wage Review, minimum award wages increased by 4.75 percent from July 1, adding to the staffing costs of businesses already managing labour shortages.
Linen is another pressure point. Robert said the small number of providers servicing the region offered limited competitive pressure on pricing.
“Operators who have not reviewed their fees and charges in several years are absorbing those increases themselves. We’ve spent much of this year working with rights operators, helping them increase or restructure their fees to help them maintain their margins,” he said.
Miriam Eagle has encountered the same reluctance among operators.
“Passing these costs onto owners is unpopular and some managers are terrified to do this,” she said.
Managers may worry about upsetting owners or losing units from their letting pool, but absorbing every increase comes at a cost to their own bottom line.
Robert warned that this pressure would continue over the next 12 months. “Managers who do not increase their charges will see their margins erode.”
Insurance has also affected the profitability and value of some coastal holiday complexes.
Antonio Curulli of MR Sales said higher premiums and tighter underwriting around severe weather risks had compressed net operating profit margins at properties with significant insurance exposure.
However, he believes conditions have begun to improve as more insurers enter the market and pricing becomes more competitive.
Protecting the letting pool
Miriam said: “The loss of units under management to owner occupiers is an ongoing problem.”
Operators also face competition from external agencies, self-management platforms and third-party short-term letting providers.
In holiday complexes, this can create more than a financial problem. Guests who book through an outside operator may still assume the onsite manager is responsible for their accommodation.
If the room is not clean or the service falls short, those guests may complain to reception or leave a negative review, despite the authorised letting agent having no involvement in the booking or stay.
On defending letting pools Robert said: “Managers who look after their owners and communicate well have been successful in maintaining the size of their pools.”

Relationships that affect the bottom line
Antonio Curulli identified strong body corporate relationships as an important characteristic of quality, saleable management rights businesses.
A good relationship can make daily operations, agreement extensions, assignment approvals and letting-pool retention much easier. Poor relationships can have the opposite effect and, in serious cases, place considerable emotional and financial pressure on managers.
Miriam said some onsite managers had been subjected to hostile emails, unreasonable demands and legal action from committee members.
“Unfortunately, some people are mean and vindictive and simply do not attempt to maintain any goodwill with their onsite managers,” she said.
“Some managers can be ruined by such activity.”
Relationship problems may not appear as a line in an income verification report, but they can still affect the value and saleability of a business.
The sales market has slowed
While operating performance is generally stable, the market for buying and selling management rights businesses has become more cautious.
Antonio described the change as a shift towards a highly analytical, “flight-to-quality” environment.
“The sector has entered a rebalancing phase. The market has shifted away from speculative pricing toward grounded operational fundamentals, and longer transaction scrutiny and timeframes to settlement,” he said.
Higher borrowing costs, tighter lending criteria, insurance concerns and greater regulatory scrutiny have changed how buyers assess opportunities.
The supply of businesses for sale has also contracted. Antonio said some owners had been reluctant to bring their businesses to market or accept offers while multipliers were below their previous peaks.
In other words, it is not only buyers who are hesitating. Some owners are also waiting for better conditions before they sell.
At the time of writing, Calvin Bailey had 14 northern properties listed but said buyers were taking much longer to make an offer.
“Many excellent properties, ones that tick all the boxes, are languishing in the ‘For Sale’ arena.”
Nevertheless, transactions are continuing. Calvin recently sold and settled three permanent management rights businesses, with another two under offer. He also reported a comparable number of holiday businesses under contract or approaching settlement.
“The perceived added security of a permanent MLR business is attracting the more conservative buyer, while the well-priced, high-earning, holiday/resort business is still attracting some quality buyers,” he said.
Activity is not uniform across the market. From her own client base, Miriam described transaction activity as particularly strong.
“From our perspective, it is a really active market.”
She said several long-term clients had recently sold their businesses, while a number of new operators had joined the firm. She estimated that her client base had averaged approximately one business transition each month over the past 18 months.
At the time of writing, her firm had four financial verifications underway and had completed another two during the previous fortnight.
Who is buying?
Permanent management rights businesses continue to appeal to first-time and mid-tier buyers seeking predictable cash flow.
Regular caretaking remuneration, often linked to CPI or an annual increase, can provide a degree of protection from changes in letting income and broader operational volatility.
Holiday and resort businesses offer higher revenue potential, but buyers are examining occupancy history, seasonal performance, guest acquisition channels, staffing costs and wage inflation more closely.
According to Miriam, a new wave of family buyers are entering the industry.
“We are seeing a wave of fresh new entrants,” she said.
“Still mostly family businesses, where people are looking for a change of pace from more demanding careers, for example corporate and farming, to a business where the whole family can be involved.”
She is also seeing more buyers acquire multiple businesses and operate them concurrently to achieve efficiencies.
Calvin has also observed growing interest from family partnerships considering larger, more expensive properties. At the same time, he has encountered opportunistic buyers seeking what he called “an unreal deal” and presenting very low offers.
There are slightly different views on corporate activity. Miriam has not seen recent active corporate buyers.
Antonio, however, has seen interest from larger corporate entities, private equity groups and experienced multi-rights syndicates in substantial resort assets.
The difference may simply come down to scale. Families and owner-operators dominate most of the market, while larger investors are generally looking at a smaller number of substantial resort businesses.
If you are considering your first purchase, read our guide to buying management rights for the first time.
Where are multipliers sitting?
Multiplier evidence varies considerably according to the size and type of business, net operating profit, agreement length, location, letting-pool strength and whether a manager’s unit is included.
Alex McCowan said short-term letting businesses with net operating profits between $300,000 and $470,000 had generally sold at multipliers between 3.2 and 3.8, with all including a manager’s unit.
There were fewer permanent sales during 2025 and 2026, but businesses earning net operating profits between $300,000 and $400,000 generally achieved multipliers of 3.9 to 4.2.
Rising real estate values had initially contributed to fewer transactions, but Alex said buyers and vendors had now adjusted to the changed market conditions.
“Real estate values have increased but not at the high levels of SE Qld and, in particular, Gold Coast and Sunshine Coast markets.”
Accom Valuers has also found sufficient market evidence to support the contracts and values it has assessed.
“Generally, contracts and values have been supported,” Alex said.
Two standout sales
Sales of larger holiday businesses earning more than $500,000 have been relatively rare, but Alex pointed to two significant transactions demonstrating continued demand for high-quality assets.
In Port Douglas, Peninsula Boutique Hotel recorded net operating profit above $1 million, including its food and beverage operations. The management rights business sold at a multiplier above 4.5, excluding the food and beverage component, delivering a return on investment above 19 percent. The beachfront property recorded average occupancy above 80 percent.
Alex described it as the most significant sale he had recorded since early 2024. The purchasers also plan to embark on a complete refurbishment of the complex and its units, reflecting their confidence in the property and the wider FNQ market.
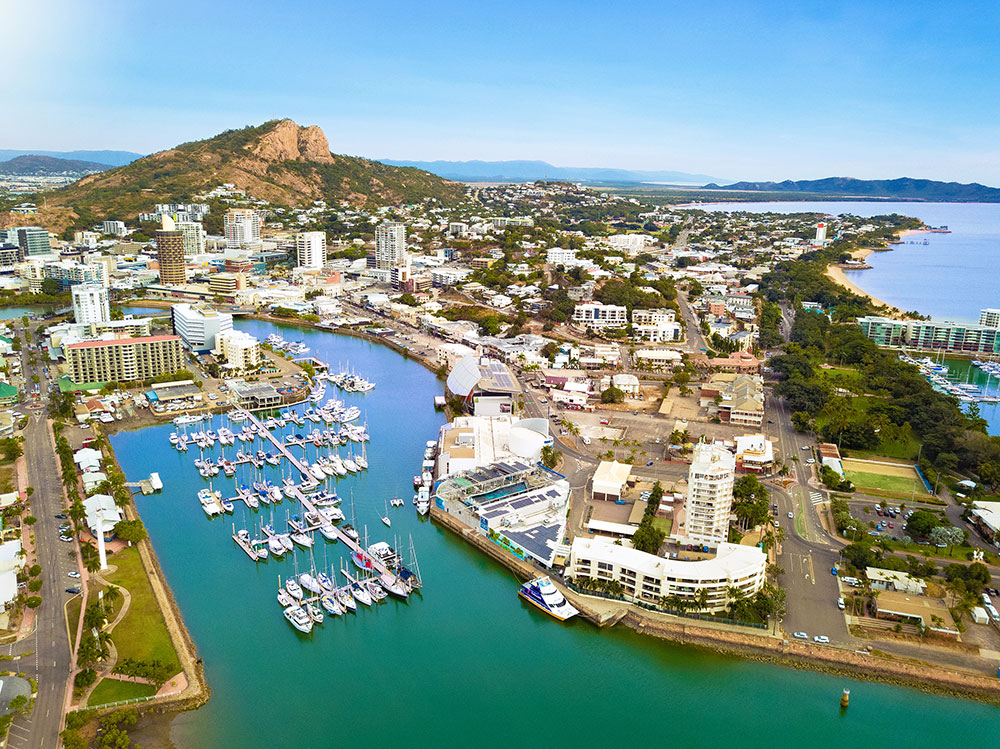
Townsville, traditionally a smaller and less active market than Cairns and Port Douglas, has also recorded increased sales activity during 2026.
Aquarius on the Beach achieved net operating profit above $1.2 million and sold at a multiplier above 4.5, representing a return on investment above 18 percent. The waterfront business had average occupancy above 80 percent and 20 years remaining on its management rights agreements.
Alex described the transaction as Townsville’s most significant management rights sale since Mariners North in 2022.
Antonio reported larger holiday and regional assets generally sitting between 3.5 and 3.9. Smaller “mum and dad” holiday complexes had experienced greater compression, with multipliers ranging from approximately 1.5 to 2.5.
Prime permanent schemes were maintaining multipliers between approximately 3.5 and 4.5, although some smaller businesses had transacted closer to 3.
Calvin’s recent sales ranged from a multiplier of 2.9 for smaller properties to 4.3 for larger businesses. His eight most recent sales totalled more than $16 million, with the largest reaching $3.3 million.
The different figures are not necessarily contradictory. Every business is different, which is why there is no single “FNQ multiplier”.
What the contributors broadly agree on is that North Queensland continues to represent value.
“Buyers are finding multipliers attractive in comparison to businesses in SE Queensland,” Alex said.
Miriam was equally clear: “Due to lower multipliers, we believe North Queensland has always been better value.”
Transactions are taking longer
Buyers may still be interested, but they are no longer rushing.
Antonio said buyers were investing more in income verification and legal due diligence, while also preparing more carefully for body corporate approval to reduce transaction risk. Transactions that once moved from offer to settlement within 60 to 90 days now regularly take between 120 and 180 days.
Financial verification has become more detailed, with specialist accountants examining several years of trading to identify non-recurring income and determine sustainable net profit.
Legal due diligence is also taking longer, particularly around body corporate authorisations, regulation module classifications, agreement terms and caretaking duties.
In some transactions, financial verification is now completed before legal due diligence begins rather than the two processes occurring simultaneously.
Committees are also undertaking more extensive character, financial and experience checks during assignment approvals, sometimes with their own legal representatives involved.
Calvin similarly reported that finance approval, due diligence and body corporate approval could extend the transaction process to at least four months.
He said it was still early days for the expanded anti-money laundering and counter-terrorism financing requirements that have applied to certain real estate and professional services since July 1, 2026. While the requirements introduce another layer of compliance, Calvin believes they should not come at the expense of the client experience.
He pointed to the framework’s reliance provisions, which he described as “a godsend”.
Where the required conditions are met, reliance is permitted within the framework and may allow an agency to use customer due diligence checks already completed by a lawyer involved in the same transaction.
“Reliance reduces admin, minimises repetition for clients and keeps transactions moving,” Calvin said.
Longer settlements can be frustrating, but buyers, lenders and advisers are clearly taking fewer chances.
Antonio believes these extended timeframes are becoming an accepted part of the industry’s risk-reduction process rather than simply a temporary barrier to sales.
Buyers are digging into the figures
Labour remains one of the most closely examined areas during financial verification.
Buyers want to understand how a business is staffed, how much work is performed by the owners and whether labour adjustments in the sale figures are realistic.
Lenders and valuers also compare each business against their financial benchmarks, although management rights businesses do not always fit neatly into a standard model.
“Management rights properties and the associated agreements are wide and varied, so sometimes extra information is required so the valuers understand why the business isn’t neatly ticking all their boxes,” Miriam said.
Common due diligence issues include missing expenses, calculation and GST errors, discrepancies between verbal representations and the sale figures, unrealistic labour adjustments and charges permitted under a Form 6 but not applied in practice.
Advertising levies, cancellation fees, commissions and guest service charges can also become problematic when the income has not been clearly disclosed to or authorised by owners.
Credit card income under scrutiny
Credit card income is a particularly important issue for businesses preparing for sale.
From October 1, 2026, card surcharges are no longer permitted for eftpos, Mastercard and Visa credit, debit and prepaid card payments. American Express has also removed surcharging from that date.
“The live issue this year is credit card income,” Robert said.
“Where a business has been recovering merchant fees from guests, that income stream disappears.”
Domestic interchange caps will fall at the same time, reducing some of the underlying costs paid by businesses. Accepting cards will not, however, become cost-free.
Operators will need to seek specialist advice about how any remaining cost can be addressed, whether through properly authorised owner charges or adjusted accommodation tariffs, with owners appropriately informed.
Where no appropriate arrangement has been made, the lost income may reduce the maintainable net profit accepted during verification.
Miriam said accountants are explaining to clients the distinction between credit card surcharges and the fees authorised through the Form 6. They need to know how to manage the owner perception the regulatory changes apply to them.
“We are recommending managers bundle the credit card fees with other commissions to avoid disharmony,” she said.
For prospective vendors, it is an issue to resolve before sale figures are prepared, not during due diligence.
Do the hard work before listing
With buyers and their advisers examining the figures more closely, preparation has become more important than ever.
Miriam said vendors should review their Form 6 agreements before going to market, particularly the treatment of credit card commissions and advertising income. All Form 6s should be properly signed, and the authorised schedule of charges should match what is being charged through the accounting system.
Complete and accurate accounting records are also essential, with any discrepancies resolved before the business is listed.
Owners should review their management and caretaking agreement terms and ensure their fees reflect current market rates or have at least increased in line with CPI where permitted.
Both Miriam and Robert recommend having the sale figures prepared by a management rights specialist accountant.
Robert said the net operating profit calculation should be no more than three months old when the business goes to market.
His advice is simple: “Do the hard work before listing.”
Minor oversights can have a material effect on maintainable profit and may ultimately lead to renegotiation on price.
As Robert explained: “None of them is difficult to fix. They simply need to be fixed before the business goes to market.”
Agreement tenure remains critical
Clean, long-term agreements remain central to business value.
Antonio identified uncertainty about future agreement extensions as an issue capable of creating valuation anxiety. He said maintaining clean, long-term agreements under the applicable regulation module remained critical to protecting business value.
Buyers are increasingly reluctant to pay premium multipliers for businesses with short agreements, declining letting pools or unresolved body corporate issues.
Today’s profit matters, but buyers and lenders also want confidence that the agreements and income will last.
Reasons for cautious confidence
The outlook is not without challenges.
Operating costs will continue to rise, buyers are likely to remain selective and transactions will take longer. Businesses with questionable income, incomplete records, short agreements or declining letting pools will face the greatest scrutiny.
Even so, there is plenty of reason for cautious optimism.
Alex said the combination of comparatively lower multipliers and strong returns continued to make North Queensland attractive to buyers. “Return on investment is strong, and this is a factor for buyers, along with lower multipliers compared with southeast Queensland markets.”
Robert pointed to growing tourism numbers and very little new holiday-letting stock as positive indicators for existing operators. He said significant projects across North Queensland, including the expansion of Cairns Hospital and other infrastructure works, should also help sustain corporate accommodation demand.
“There is very little new holiday-letting stock entering the market whilst tourism numbers continue to grow. This puts existing operators in a strong position,” he said.
From the level of accounting and transaction activity he has seen, Robert believes the sector has moved beyond the effects of the pandemic and that North Queensland is again being viewed as a sound investment destination.
Antonio also expects sales activity and multipliers to improve as borrowing costs ease, lender competition strengthens and buyers reassess their options following a substantial reduction in the availability of motel, caravan park and other accommodation investments.
“We expect that the market is in a rebalancing phase with multipliers starting to turn back upwards. Well-located complexes with long contractual tenure, verified net profit, sustainable history of at least CPI growth and strong body corporate relations continue to attract solid buyer competition,” Antonio said.”
Miriam expects new operators entering the industry to bring fresh energy to the North Queensland market.
Calvin remains cautious about current enquiry levels but confident in the strength of the underlying business model.
“The management rights market continues to demonstrate impressive resilience,” he said.
“The market is transitioning from an aggressive growth cycle into a more balanced and sustainable phase, one that continues to reward quality assets and realistic vendor expectations.”
Calvin sees particularly strong opportunities in Port Douglas and the Cairns Northern Beaches. He said Cairns, Townsville and Airlie Beach also offered buyers more resort for their dollar than many markets further south.
“Cairns itself has some really great opportunities across all types of properties.”
He pointed to recurring income, long-term agreements, CPI-linked caretaking remuneration, residential lifestyle benefits and relatively low staffing exposure in many complexes as enduring strengths of the management rights model.
“These fundamentals remain attractive to owner-operators, semi-retirees and experienced accommodation operators alike.”
Lifestyle, accessibility and support
ARAMA CEO Trevor Rawnsley agrees that the challenges identified by the contributors are real but believes the figures tell only part of the story, with many of the advantages of living and operating in FNQ too easily overlooked.
He is sensing increased optimism across North Queensland, reflected in growing ARAMA membership, and believes the region’s lifestyle advantages deserve more attention.
“North Queensland offers a more laid-back and casual environment, which should be a significant drawcard.”
Trevor believes lower multipliers make the region more accessible to first-time buyers, particularly families, while offering the potential for stronger returns.
“There is an old saying that goes something like, ‘The city for show and the regions for dough.”
Trevor said buyers and existing operators should also be aware of the training, education and support available through ARAMA. Much of its training is offered to members at no additional charge and includes Type 1 and Type 2 continuing professional development.
ARAMA’s five-day induction program combines three days of intensive classroom training with two days of practical mentoring from an ARAMA-accredited mentor, including mentors based in North Queensland.
The association also plans to release its latest fees and charges survey later this year, which will be available to members at no additional cost. Face-to-face education sessions are also planned for Cairns, Port Douglas and other regional locations during October and November, helping operators learn how to review and confidently increase their fees and charges.
Trevor said these programs were designed to help operators deal with many of the issues raised in the report.
“The challenges are real, but there are also remedies, training and support available for those operators and professionals who choose to use them.”
So, what is the state of North Queensland’s management rights industry?
The businesses themselves are generally steady. Holiday trading has strengthened, occupancy is sound and well-managed operations continue to produce attractive returns.
The sales market is more subdued. Buyers are cautious, finance and due diligence are taking longer, and yesterday’s peak price is not automatically today’s market value.
The post-pandemic rush may have passed, but the opportunities have not disappeared. Buyers are simply more careful about what they buy and what they pay.
Sellers will need realistic expectations and their paperwork in order. For buyers prepared to do their homework, North Queensland still offers lots of value and opportunity.
Quality businesses are still selling; buyers are just looking harder before they leap.
Disclaimer: The figures and market information in this report were supplied by the contributors and were considered accurate to the best of their knowledge at the time of writing. This article provides general industry information only and does not constitute financial, legal, accounting or investment advice. Readers should obtain advice from appropriately qualified professionals before making business or investment decisions.
Related Content
Latest issue of Resort News Accommodation for Sale Latest Industry News